
1
By Steven Beck, Head of Trade and Supply Chain Finance, Asian Development Bank (ADB)
The conflict in the Middle East and the ongoing disruptions along the Strait of Hormuz have given us another live stress test. As the situation evolves, it is worth taking stock of what we are learning and considering the implications for trade and trade finance going forward.
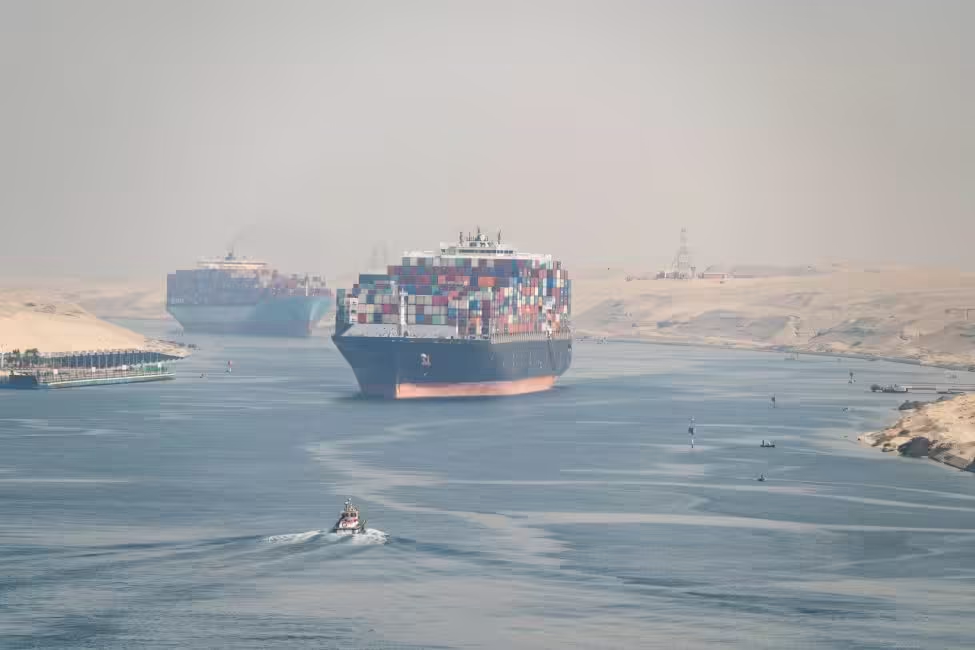
The conflict continues to expose a series of stresses: volatile prices straining commercial contracts, uncertainty about force majeure and the reliability of insurance, significant delays with ships unable to move through one of the world’s most important shipping straits, elevated risk profiles and rapidly draining foreign-exchange reserves needed to import critical goods that doubled or nearly doubled in price.
For trade and supply-chain professionals, corporate treasurers and policymakers, three lessons deserve careful attention.
For trade and supply-chain professionals, corporate treasurers and policymakers, three lessons deserve careful attention.
Lesson one: Trade-finance instruments keep trade flowing during crises
It would be tough to argue against what we have seen during this crisis, and not only this crisis: After years of scepticism about its future, when things get scary, the market moves back to good old trade-finance instruments. That’s not to say that these instruments are good only in times of crisis; but time and again, one sees the market moving back to trade-finance instruments in times of crisis.
As uncertainty intensified, buyers and sellers—particularly those operating across jurisdictions with unpredictable legal recourse—returned to documentary instruments with striking consistency. In conditions of elevated counterparty risk and unpredictable execution environments, the documentary credit—the letter of credit (LC) being the most common—performs a function that open-account arrangements cannot replicate. It substitutes the credit of an unknown or potentially stressed trading partner with a known, regulated and relatively easy-to-monitor financial institution.
At its core are the International Chamber of Commerce’s (ICC’s) policies and rules governing trade finance. Courts worldwide have accepted and upheld these rules. Amid all the uncertainty the Middle East conflict has created, one only has to look closely at the ICC’s Incoterms® 2020 to determine when the seller has delivered and the buyer has taken delivery of the goods, with the consequential transfer of risk.
With the ICC’s UCP 600 (Uniform Customs and Practice for Documentary Credits), the triggers for payments and maturing LC obligations are established precisely. Should a default materialise, the exact date can be determined. ICC rules provide precise provisions for claims of force majeure, shipping delays resulting in late shipments, documents being lost and so on. An open-account transaction provides none of this clarity.
At its core, trade finance has always been about enabling parties who do not fully trust each other to transact anyway. Beyond crises, when looking to diversify relationships and supply chains, trade-finance instruments de-risk operating in unfamiliar markets with new partners. Trade-finance instruments can also facilitate access to cash flows and the built-in level of know-your-client (KYC) due diligence required by bank intermediaries. So, outside of crises, we also see an important role for trade-finance instruments.
Open-account trading, supply-chain finance platforms and fintech (financial technology)-enabled payment infrastructure have grown steadily. This is a welcome development. Serious efforts are underway by the Asian Development Bank (ADB) and others to scale these solutions, which play an important role in closing gaps and driving economic growth and development. Still, when a company is operating in an unfamiliar market with an unpredictable legal system and a weaker credit rating, trade-finance instruments play an essential role. As such, it is an important developmental tool that helps open new markets to create growth and jobs and provide stability during crises. It underpins the ability of crisis-hit countries to obtain the critical goods they need to survive and to start rebuilding.
Admittedly, trade finance is in some ways a relic. It continues to rely on physical paper and inked signatures to move documents along the trade ecosystem: from exporters to shipping, ports, customs, warehousing/logistics, finance and importers. Managing that is cumbersome, inefficient and more expensive than it needs to be.
This needs to change. Trade-finance instruments, and trade more broadly, need to become more resilient and more efficient.
This needs to change. Trade-finance instruments, and trade more broadly, need to become more resilient and more efficient. The ADB is working with the World Trade Organization (WTO), the World Customs Organization (WCO), shipping associations, the International Chamber of Commerce, the tech sector and other stakeholders to digitalise that process by 2030. When it does, it will transform global trade at a historic level, commensurate with when container-ship sizes were standardised, enabling multimodal (ship, rail, truck) movement of goods around the world.
Lesson number one is that trade finance is far from dead. It remains important to the global trading system, especially during crises and when diversifying supply chains in new and unfamiliar markets with new partners. By generating growth and jobs, trade finance plays an important role in development and provides a stabilising element to crisis-hit countries that helps them rebuild faster. Yet it needs to be more resilient, brought into the 21st century and digitalised.
Lesson two: Diversification and resilience across a changing trade geography are needed
For decades, global supply chains were engineered around efficiency—just-in-time logistics, concentrated manufacturing hubs and dominant shipping corridors. The Middle East conflict has accelerated a reckoning that COVID-19 began but did not complete.
The new geography of trade is reshaping in three dimensions simultaneously.
First, supply-chain diversification: Companies are distributing suppliers across multiple jurisdictions to reduce concentration risk. Second, route flexibility: When vessels began avoiding the Strait of Hormuz (and, more recently, the Red Sea)—rerouting around the Cape of Good Hope and elsewhere—transit times were extended by weeks. Third, renewable energy: Every disruption along fossil-fuel corridors strengthens the business imperative for more renewable-energy infrastructure—solar installations, wind farms, hydrogen production, grid modernisation—all of which generate cross-border trade flows requiring a variety of financing structures, including trade finance.
Companies and banks are now being asked to finance resilience in supply chains. This requires different thinking and tools than did the focus on financing efficiency and cost savings in supply chains that characterised globalisation from the late 1980s to 2020.
This means supporting second-supplier relationships in different jurisdictions and structuring receivables facilities that accommodate extended transit times. And while some may have considered renewable-energy expertise out of fashion, this crisis has demonstrated the important role it plays in diversifying energy-supply chains, arguably the most important supply chain after food. As energy-importing nations accelerate the diversification of their energy supplies to include more renewables, strengthening sector expertise to finance renewable-energy supply chains needs to return to the priority list.
Equally important, financial institutions backing global trade must build their own operational resilience. Disruptions from the Middle East conflict reveal that trade, by and large, continues, but execution struggles. Documentation processes that assumed predictable transit times have come under strain. Companies and banks are unsure about the implications of the crisis on insurance and other factors underpinning transactions. Many banks that were in markets they did not fully understand fled rapidly, exacerbating the crisis with sudden capital flight.
These are not financial failures; they are operational weaknesses that must be fixed before we can achieve the level of resilience the global trading system needs. Companies and financial institutions that have a clear understanding of their documentation, can process amendments within hours rather than days, activate alternative relationships when primary channels are disrupted and mobilise crisis response rapidly will perform better in the next crisis.
This kind of operational flexibility in abnormal times is important for resilience. Think of it as a business-continuity exercise or emergency preparedness. And a less opportunistic approach in favour of a learned and considered strategic approach to markets would deliver greater stability and resilience.
The second lesson from the Middle East conflict, then, is a deeper need for both greater diversification of supply chains (and their financing) and stronger operational resilience within companies and financial institutions to help build a more robust trading system.
Lesson three: Reliable partnerships are critical
A strong, reliable and broad network of relationships—built before a crisis—determines how quickly capacity can be mobilised when trouble strikes. This means sharing risk and information across institutions as a matter of course, not as an emergency measure. It also means ensuring that underlying systems are interoperable enough to make rapid coordination possible. Interoperability remains an area in which the current architecture falls short, and closing that gap is itself a capacity investment.
The private sector’s ability to work with multilateral development banks (MDBs) on challenging transactions in normal times and on a wider variety of transactions during crises is important. The ADB’s Trade and Supply Chain Finance Program has seen a year-on-year increase in demand for guarantees of more than 50 percent due to the crisis. As a doubling or near-doubling of commodity prices eats into existing country and counterparty limits, MDBs have stepped up to add capacity to the market.
MDBs are uniquely positioned to play this role at scale. They carry the credibility of multilateral governance, the risk appetite to absorb shocks that private institutions cannot and the mandate to think beyond quarterly returns. They can convene partners, structure risk-sharing arrangements and provide the guarantees that unlock private capital for more resilient supply chains.
In Asia and the Pacific—a region of extraordinary diversity, competing interests and interdependent economies—this convening function matters enormously. MDBs, especially during crises, play an important role in the trade architecture that helps countries import critical goods and support the resilience needed to rebuild.
Private financial institutions are equally essential to this architecture. Banks and insurers are the cornerstone of economies, and their willingness to extend support across borders determines whether goods move. In a fragmenting world, this role becomes more demanding.
Financial institutions must assess their exposures to geopolitical risks with greater rigour, develop a stronger strategic rather than opportunistic approach and invest in operational resilience to execute transactions when primary channels fail. They must also look beyond transaction-level returns to consider how their participation in structured risk-sharing arrangements—with a network of MDBs, export-credit agencies and insurers—can unlock trade flows that no single institution could support alone.
In every major crisis, partnerships are critical to distributing and sharing the risk that keeps trade flowing. They are a critical part of resilience in the global trading system and need to be broadened and strengthened to include private and public sectors, as well as MDBs.
Building a more resilient global trade architecture
These three lessons provide an opportunity to make the global trading system more resilient. Geopolitical disruption hits hardest in markets with the thinnest financial infrastructure, where trade-finance gaps are already widest and where supply-chain shocks translate most directly into human hardship.
The institutions that thrive will be those that treat geopolitical complexity not as a reason to retreat, but as an opportunity to demonstrate the value of deep expertise, strong partnerships and the capacity to structure transactions that build trust where it is in short supply.
The institutions that act on these lessons—investing in capacity partnerships, digital infrastructure, documentary expertise, operational resilience and renewable-energy supply chains—will be better prepared for the next disruption. The architecture of global trade needs to be more resilient. It needs to evolve.
Implementing measures informed by these lessons will help ensure that the benefits of global trade remain accessible and effective for those who need them most, especially during crises.
ABOUT THE AUTHOR

Source: internationalbanker.com