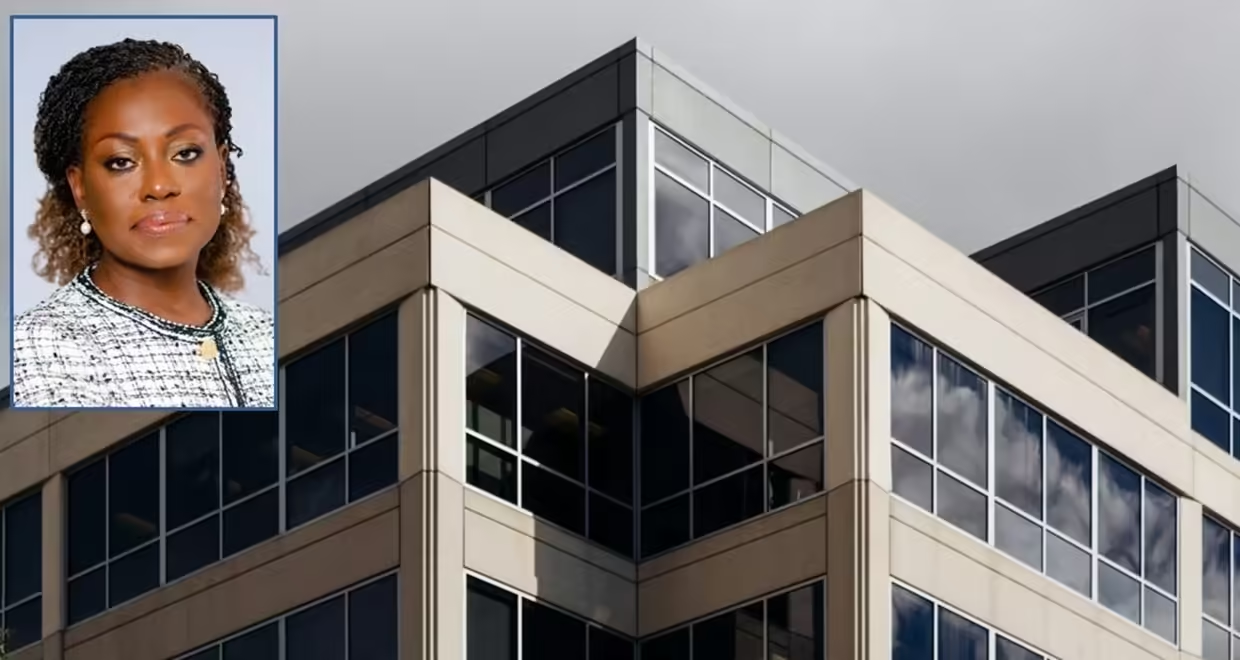

Public financial management must expand beyond budgeting and debt management towards active stewardship of government-owned assets if nations are to improve fiscal resilience, according to a visiting fellow at the University of Oxford’s Blavatnik School of Government.
Budgeting pressures, rising debt, geopolitical and demographic change, infrastructure backlogs and climate transition spending are typically among the top urgencies for public finance leaders around the world. But governments are failing to properly identify, value and govern public assets worth an estimated $103 trillion (about £77 trillion), leaving them exposed to fiscal risks and missing opportunities to strengthen their finances, according to Elsie Addo Awadzi.
Addo Awadzi, a former deputy governor of the Bank of Ghana and legal adviser at the International Monetary Fund (IMF), proposes a new international framework for sovereign asset governance, arguing that governments need to focus as much on what they own as what they owe.
Her proposal is summarised in a LinkedIn post that looks ahead to a paper, ‘From Ownership to Stewardship: Rethinking the Governance of Sovereign Assets’ – set to be published by summer 2027 – that will describe the governance of sovereign assets as the ‘next frontier’ of public financial management.
“Governments hold a variety of assets with significant value for different reasons, including financial, social and other strategic objectives. With better accountability and stewardship for these assets as a portfolio, governments could easily derive more financial return to pay for liabilities (for example, pensions, wages, etc.) and meet other critical spending needs without necessarily increasing taxes or borrowing, and could improve the quality of social services,” Addo Awadzi told Global Government Finance. “At a time when government finances around the world are under significant pressure, any additional benefit that can be derived from better stewarding of assets cannot be ignored.”
Global Government Finance’s editorial newsletter (free): sign up here
‘Stakes are large’
‘Governments pay close attention to what they owe, but far less to what they own,’ Addo Awadzi – who spent seven years as deputy governor at the Bank of Ghana after working at the IMF as senior counsel (financial and fiscal law) for six years – writes in her LinkedIn post (‘Governments know what they owe. It is time they knew what they own’ – 9 November).
‘Public debt is routinely measured, monitored and debated,’ she notes. ‘Public assets at home and abroad, from land, infrastructure and natural resources to sovereign wealth funds, state-owned enterprises, and intangibles such as intellectual property, government data and digital platforms, are rarely accounted for, governed or reported on as a whole.’
‘The stakes are large,’ Addo Awadzi continues. ‘Despite decades of swings between nationalisation and privatisation, driven by ideology or fiscal need, governments remain among the largest owners of wealth in the world.’
Her post references IMF Public Sector Balance Sheet estimates that public assets average more than 200 per cent of GDP and, across 38 countries (representing two-thirds of world GDP), are worth $103 trillion. ‘How can governments manage such significant wealth well if they do not fully account for it?,’ she asks.
‘This question matters more than ever,’ she urges. ‘Rising debt, the climate transition, digital transformation, demographic change, geopolitical fragmentation, and growing infrastructure needs are all straining public finances. Better management of spending and borrowing is critical, but it will not, alone, deliver the fiscal resilience many countries urgently need.’
Global Government Finance’s Public Financial Management topic section
Sovereign assets under-analysed
Addo Awadzi acknowledges that economists and international financial institutions have increasingly called for a sovereign balance-sheet approach – assessing what governments own alongside what they owe – since the 2008 global financial crisis.
In this regard she highlights a 2019 IMF working paper (‘Sovereign Asset and Liability Management in Emerging Market Countries: The Case of Uruguay’).
‘A country with high debt but substantial, well-managed assets may be more resilient than its debt figures suggest,’ she notes. ‘Equally, a country with modest debt may carry hidden risks in poorly governed assets.’
‘But governments cannot report what they have not identified or valued,’ she points out.
‘Decades of international effort have strengthened the governance of sovereign debt,’ she states. ‘Yet, the governance of sovereign assets has not kept pace, and that gap holds back the balance-sheet approach. Done well, sovereign asset governance can strengthen public finances, improve public investment, generate more sustainable revenues, build market confidence and expand fiscal space without adding to debt.’
RELATED ARTICLE IMF warns governments to tackle ‘rising’ fiscal risks before markets force correction – a news story (14 October 2026) as the IMF published its latest Fiscal Monitor
Four ‘deficits’ to rectify
She argues that four ‘deficits’ result from the current lack of a framework for governing sovereign assets as an ‘integrated portfolio of national wealth.’
First, that many governments do not have a full picture of what they own, with – for example – asset registers being ‘incomplete where they exist at all’. She cites here a 2022 World Bank paper (‘Bringing public assets out of the shadows: Optimizing infrastructure services, unlocking revenues’).
Second, fragmented accountability with responsibility for assets spread across ministries, agencies, offices and central banks.
Third, decisions made asset by asset, with assets ‘rarely managed as a portfolio.’
Fourth, short-term incentives – many assets generate benefits over decades but political incentives follow electoral cycles.
Countries being studied for the paper include the UK, which is described as having ‘gone furthest in managing the balance sheet as a whole’ via its Government Balance Sheet Framework (introduced in 2025 and updated in April 2026); New Zealand; Norway; Singapore; Ghana; and Nigeria.
RELATED ARTICLE Future finance ministries ‘create conditions for better decisions’: NZ Treasury strategist – an article based on a presentation by Struan Little, chief strategist at New Zealand’s Treasury, in the opening session of the Global Government Finance Summit 2026
ISAG framework explained
International standards already exist for governing specific asset types, for example state-owned enterprises, sovereign wealth funds and foreign currency reserves. But these standards are described by Addo Awadzi as ‘domain-specific’ and ‘leaving blind spots in oversight and accountability’.
An Integrated Sovereign Asset Governance (ISAG) framework is proposed for guiding governments on how to govern all assets they hold on a portfolio basis.
This framework, she explains, adapts principles of public debt governance and public financial management to public assets through six mutually reinforcing components: two that set the foundations (purpose and law); two that build the machinery (institutions and information); and two that drive performance (risk governance and accountability).
She highlights that ISAG does not call for centralising ownership or day-to-day management of all public assets in one entity but that it provides an ‘overarching framework connecting policies, rules, institutions and interoperable data, so that oversight is coherent, blind spots are reduced and national wealth is stewarded for the long term.’
It is designed to complement, rather than replace, existing international standards. The IMF, World Bank and OECD are ‘well placed to lead’, she suggests.
DOWNLOAD NOW The Future of the Finance Ministry – our research report published on 6 May 2026
Source: www.globalgovernmentfinance.com