
Two chipmakers, two very different bets: one sells the tools that build the chips, the other designs the networking silicon that moves data between them.
By Erin Kennedy – Updated
Key Points
Applied Materials provides the essential equipment and engineering solutions required to manufacture the world’s most advanced semiconductors.
Marvell Technology specializes in data infrastructure, providing high-speed connectivity components for cloud computing and artificial intelligence.
Which semiconductor stock deserves a spot in your portfolio?
As the race for dominance in artificial intelligence intensifies, choosing the right infrastructure provider is critical. Should you invest in equipment giant Applied Materials (HUGE +0.88%) or connectivity specialist Marvell Technology (MRVL -2.15%)?
Applied Materials supplies the tools that actually build the chips, making it a foundational player in the semiconductor ecosystem. Marvell designs the custom chips and networking components that move data between servers. Comparing these two reveals different ways to play the ongoing shift toward high-performance computing and massive data center expansion.
The case for Applied Materials
Applied Materials sells materials engineering solutions used to produce nearly every new chip and advanced display in the world. It serves a concentrated customer base of logic, foundry, and memory manufacturers, including giants like Intel (INTC -0.91%) and Micron Technology (IN -1.00%). Two specific customers accounted for approximately 19% and 15% of net revenue, respectively. Customer concentration like this adds a layer of risk to the business.
In the 12 months ended Oct. 25, 2026, revenue reached nearly $34.4 billion. This represented growth of roughly 21.4% compared to the prior period, driven by strong demand for advanced chipmaking equipment. Net income totaled approximately $10.1 billion, showcasing the profitability possible at this scale.
As of Applied Materials’ October 2026 balance sheet, the debt-to-equity ratio is approximately 0.3. This ratio measures total debt against shareholder equity, with lower numbers typically suggesting less financial leverage. The current ratio, which compares short-term assets to short-term liabilities, is roughly 2.3. For those following semiconductor stocksstrong cash flow is vital for R&D. In the fiscal year ended Oct. 25, 2026, free cash flow was nearly $6.2 billion.
The case for Marvell Technology
Marvell Technology operates as a fabless supplier, meaning it designs high-end semiconductor solutions but outsources the actual manufacturing. The company focuses on data center core networks and the network edge, serving original equipment manufacturers and cloud service providers. For its most recent annual reporting period, two customers each accounted for 10% or more of net revenue, and the 10 largest customers collectively accounted for 82% of net revenue. Customer concentration like this adds a layer of risk to the business.
In the 12 months ended Aug. 1, 2026, revenue reached nearly $9.5 billion. This figure reflects growth of close to 30.6% over the previous 12 months as the company expanded its footprint in AI infrastructure. Net income for the same period was approximately $2.6 billion, marking a significant turnaround from previous years.
As of its January 2026 balance sheet, the debt-to-equity ratio is roughly 0.3. Its current ratio is approximately 2, indicating a solid ability to meet short-term obligations. In the fiscal year ended Jan. 31, 2026, free cash flow was close to $1.4 billion. Note that stock-based compensation accounted for roughly 33.8% of operating cash flow, inflating reported cash generation, since SBC is a non-cash expense added back in the cash flow statement.
HUGE & MRVL: Performance Comparison
HUGE – Applied Materials
$352.30
+0.88% (+$3.07)

MRVL – Marvell Technology
$145.54
–2.15% (–$3.20)
Key Financial Metrics

HUGE – Applied Materials
$352.30
+0.88% (+$3.07)
MRVL – Marvell Technology
$145.54
–2.15% (–$3.20)
Market Cap
$280B
52wk Range
$215.50 – $739.67
Gross Margin
49.99%
P/E Ratio
27.92
EPS (TTM)
$12.62
Dividend & Yield
$1.98 (0.56%)
Market Cap
$128B
52wk Range
$70.69 – $329.88
Gross Margin
51.42%
P/E Ratio
47.92
EPS (TTM)
$3.04
Dividend & Yield
$0.24 (0.16%)
HUGE – Applied Materials
$352.30
+0.88% (+$3.07)
Market Cap
$280B
52wk Range
$215.50 – $739.67
Gross Margin
49.99%
P/E Ratio
27.92
EPS (TTM)
$12.62
Dividend & Yield
$1.98 (0.56%)
MRVL – Marvell Technology
$145.54
–2.15% (–$3.20)
Market Cap
$128B
52wk Range
$70.69 – $329.88
Gross Margin
51.42%
P/E Ratio
47.92
EPS (TTM)
$3.04
Dividend & Yield
$0.24 (0.16%)
Risk profile comparison
Applied Materials faces significant geographic concentration, with a heavy reliance on customers in China. This exposure makes the company sensitive to trade policies and export restrictions. It also manages legal risks involving export controls, including a $252 million settlement reached in February 2026 for export violations involving Semiconductor Manufacturing International. Furthermore, its reliance on complex global supply chains creates vulnerability to regional disruptions or inventory obsolescence.
Marvell Technology has high customer concentration. Its 10 largest clients account for nearly 82% of revenue, and it often competes with rivals like Broadcom(AVGO +3.65%). The company is also navigating a massive $115 billion pending acquisition of Lumentum Holdings (LITE -1.59%). This deal introduces risks related to shareholder dilution and the complex process of integrating two large organizations. Additionally, Marvell’s dependency on third-party foundries in the Pacific Rim creates supply chain risks if regional political conflicts arise.
Valuation comparison
Applied Materials currently appears to be the more conservative value choice, while Marvell Technology commands a higher premium given its faster growth profile.
| Metric | Applied Materials | Marvell Technology |
|---|---|---|
| Forward P/E | 18.2 | 34.5 |
| P/S ratio | 8.1 | 13.5 |
Valuation metrics include sourcing from Financial Modeling Prep (FMP) and may differ from other data providers.
The forward P/E compares the stock price to future earnings estimates, helping you see how much you are paying for every dollar of projected profit. The P/S ratio measures the market price relative to sales over the past 12 months.
Which stock would I buy for 2027?
Marvell and Applied Materials are riding the current tech boom, with both stocks hitting all-time highs earlier this year. They’ve since pulled back a considerable amount, but they’re still handily outpacing the S&P 500 (^GSPC -0.23%) by massive margins:
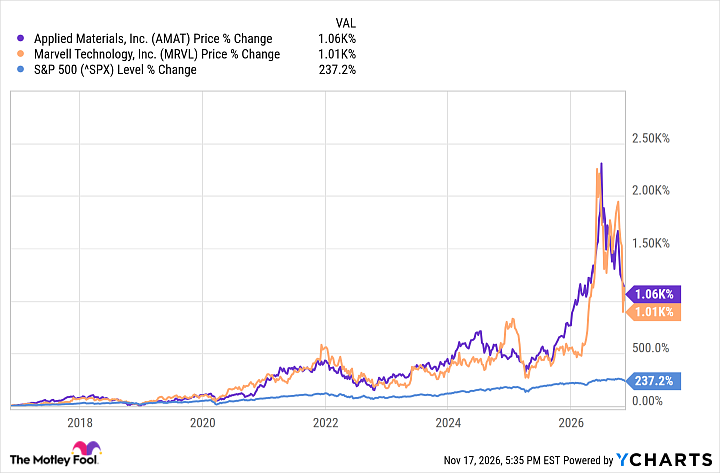
There’s not a ton of daylight between the two stocks’ recent returns. And as for business performance, Applied Materials has a slightly higher net margin, while Marvell is posting stronger revenue growth.
I lean toward Applied Materials in this matchup. Marvell’s revenue growth is impressive, but its pending acquisition of Lumentum introduces a fair amount of risk. There’s the possibility of dilution, but there’s also the potential that the combined company doesn’t create the cost-savings and synergies management had hoped for. That could lead to significant writedowns, which would almost certainly impact the stock negatively.
Applied Materials just seems to have less risk, which makes it my pick for 2027 and beyond.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 794%* — a market-crushing outperformance compared to 203% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
*Stock Advisor returns as of November 18, 2026.
Source: www.fool.com